




Blog
SPAC New Rules Take Effect: Nasdaq Threshold Raised, OTC-to-Listing Green Channel, CNY 25 Million Standard for Chinese Issuers – How Should Chinese Companies Choose
In August 2026, three major new rules for the SPAC market were fully implemented: the Nasdaq SPAC listing threshold was raised, the SEC accelerated the OTC-to-listing green channel, and a $25 million minimum standard for Chinese founders. This is not a tightening, but rather opening up clearer rule boundaries for Chinese companies to list in the U.S..
When Nasdaq set a $25 million fundraising threshold for Chinese company IPOs in May 2025 and the SEC’s 2024 SPAC new rules remained in effect, the entire SPAC market was waiting for "rule clarification". From December 2025 to April 2026, the three new rules were implemented one after another, finally giving Chinese companies a predictable rule framework for their U.S. SPAC path.
This article provides an in-depth review of the specific content of the three new rules and their impact on Chinese companies, helping Chinese companies find the most suitable capital path for themselves under the new rule framework.
I. Overview of the Three Core Changes to the SPAC New Rules
From the end of 2025 to the first half of 2026, the SPAC market saw three core regulatory changes:
Three Core Changes to the SPAC New Rules
① Nasdaq SPAC Listing Threshold Raised (2026/4)
→ Global Market: Market value of listed securities $75 million → $100 million, while maintaining the requirement of 400 public shareholders
② OTC-to-Listing Green Channel (2025/12)
→ Delisted SPACs, after completing De-SPAC, can apply to return to Nasdaq directly without the reverse merger restriction
③ $25 Million Standard for Chinese Founders
→ Companies with primary operations in China (including those that, after merger, must meet the $25 million unrestricted public float market value requirement
These three changes together outline the new rule framework for the SPAC market: higher quality thresholds, unblocked exit channels, and standardized Chinese regulations. For Chinese companies, this is not closing the door, but opening a clearer entrance for compliant Chinese companies.
II. Detailed Explanation of NASDAQ SPAC Listing Requirements
In April 2026,the new NASDAQ SPAC listing rules officially took effectand comprehensively raised the admission standards for different segments:
| Segment | Metric | Old Rules | New Rules |
|---|---|---|---|
| Global Market | Market capitalization of listed securities | USD 75 million | USD 100 million |
| Number of public shareholders | 400 | 400 (unchanged) | |
| Capital Market | Listing market capitalization | USD 50 million | USD 75 million |
| Public float market capitalization | USD 15 million | USD 20 million | |
| Market makers | 3 | 4 | |
| Number of public shareholders | 300 | 400 |
Data confirms the screening effect of the raised threshold:SPACs listed on the Nasdaq Global Market in Q1 2026 all had an issuance size of no less than $100 million; while in the same period of 2025, 11 SPACs had a market capitalization below $100 million.
This"threshold adjustment"may seem strict on the surface, but it actually helps the marketeliminate weak SPACs and retain strong ones,allowing Chinese enterprises to find "higher-quality SPAC partners".
III. Detailed Explanation of OTC Transfer Green Channel
In December 2025,the SEC approved the rule revision submitted by Nasdaq through accelerated review, providinga green channel for transferto eligible SPACs on the OTC market.
Core content:
• SPACs that were previously listed on a national securities exchange and then delisted to OTC, after completing a De-SPAC merger,may be exempt from regulatory restrictions and average daily trading volume requirements related to the reverse merger
• Directly apply to return to the Nasdaq Main Board,simplifying the path and lowering the threshold
This adjustment has important structural significance:it opens a new exit channel for existing SPAC assets, and also provides enterprises that temporarily cannot meet the main board IPO requirements withthe "OTC-SPAC merger - transfer" detour path.
But the relaxation is not without limits: the rules clearly require SPACs must retain core protection mechanisms such as investor redemption rights, and the merger transaction must be completed in accordance with the effective registration statement.
4. Detailed Explanation of the $25 Million Minimum Standard for Chinese Founders
Nasdaq has set special additional standards forcompanies with principal operations in China (including Hong Kong and Macau).
Core requirement: Chinese-background companies listed via methods such as SPACs andreverse mergersmust meet a minimum of $25 million in unrestricted public float market capitalization after the merger.
Key points of this threshold:
① Significantly higher than the standard for regular issuers: The Nasdaq standard for regular issuers is $15 million in public float market capitalization, which is67% higher for Chinese-background companies.
② Reduces operational space for small and medium-sized Chinese companies: Small and medium-sized Chinese companies with revenue in the tens of millions of RMBstruggle to meet the $25 million standard alone and need to use OTC tiered incubation.
③ Promotes improvement in compliance quality: The high threshold forces Chinese companiesto establish compliance practices and secure institutional coverage during the OTC stage,laying a solid foundation for uplisting.
For Chinese-background companies, the $25 million standard is both a challenge and an opportunity.It reminds Chinese companies that the "direct uplisting to the main board" path requires sufficient capital support, while OTC tiered incubation is a more realistic choice.
5. SPAC Path Decisions for Chinese Companies Under the New Rules
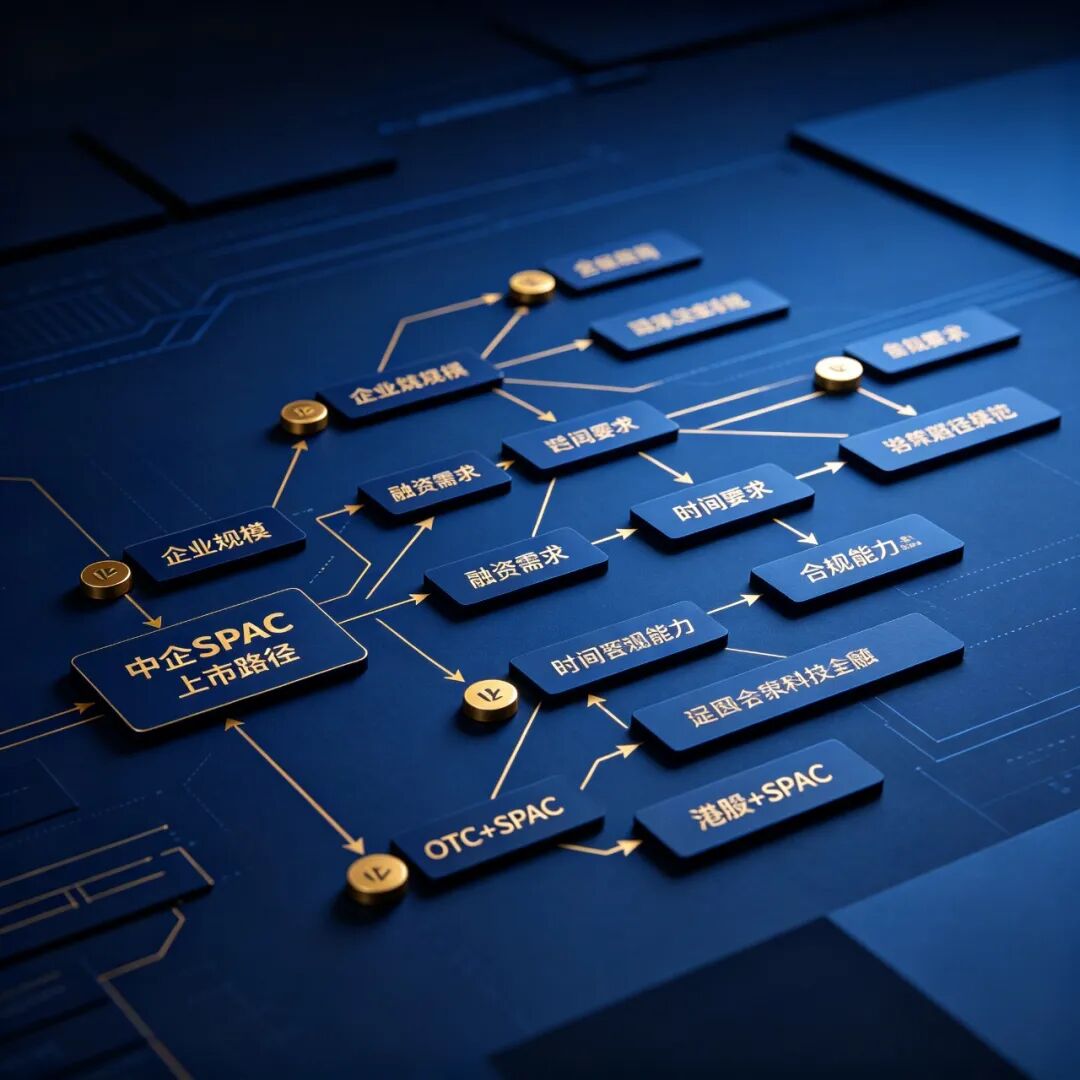
After the three new rules take effect, how should Chinese companies choose a SPAC path? The key depends on five dimensions:
Five Decision Dimensions for Chinese Companies' SPAC Paths
① Company size: Revenue in tens of millions of RMB vs. hundreds of millions of RMB
② Financing needs: Urgency and scale
③ Compliance Basis: Does the company already have an overseas structure and financial reporting system
④ Timeline Requirement: Is a quick listing status required
⑤ Consultation Requirement: Is professional guidance needed
SPAC Path Selection Under Different Dimension Combinations:
• Large Enterprise + High Financing + Full Compliance → Direct NASDAQ SPAC Merger
• Hong Kong Stock Exchange Listed Company + Dual Platform → Hong Kong Stock Exchange + SPAC Dual Listing
• Small and Medium-sized Entity + Weak Compliance + Long Cycle → OTC + SPAC Step-by-Step Upgrade
Golden Box Enterprise Management Group is exactly the professional companion on this path:
① Path Selection: Based on the enterprise's size, compliance foundation, and business needs, accurately match the most suitable SPAC path.
② Rule Interpretation: In-depth interpretation of the specific impact of the three new regulations on enterprises, provide pre-compliance advice.
③ Full-Process Guidance: From OTC shell selection, SPAC matching, cross-border structure design to listing application, Golden Box provides exclusive data insights on 848 Chinese enterprises + full-path professional guidance.
With the implementation of the three new regulations, the "rule dividend period" of the SPAC market has officially begun.Smart enterprises have already started acting——The earlier you understand the new regulations, the earlier you layout compliance, the earlier you seize the SPAC dividend window.
Nasdaq threshold increase, OTC transfer board green channel, Chinese founder 25 million standard —Three new rules together outline the "new rule boundaries" of the SPAC market.Chinese enterprises that understand these rules can find their own "rocket orbit" in the new SPAC era.
Originally published on 金盒企业管理集团
